Writing a Treasury Policy Your Board Will Sign: A 2026 Template
 Copied!
A board ready 2026 treasury policy guide with practical rules for liquidity, counterparties, concentration, authority, exceptions and a copyable policy template.
A board ready treasury policy turns risk appetite into clear operating authority. It states why cash is held, what liquidity must remain available, where money may sit, who can move it, how exceptions are approved and when the board will review the rules. The best policy is specific enough to govern real decisions.
TL;DR
- It states why cash is held, what liquidity must remain available, and where money may sit.
- It sets who can move money, how exceptions are approved, and when the board sees it again.
- The guide covers how to set counterparty and concentration limits.
- It covers who is authorised to move money and up to what value, and how often the policy is reviewed.
- It includes a full template and how to take it to the board.
See how Round brings cash visibility and finance workflows together
This guide provides a practical structure and a copyable template. It is general information, not legal, tax, accounting or investment advice. The final policy should reflect the group's legal entities, financing documents, bank mandates and local requirements, with specialist review where appropriate.
What is a treasury policy and who needs one?
A treasury policy is the board approved framework for managing cash, liquidity, banking, payments, funding and financial risk. It sits above procedures. The policy says what is allowed, who has authority and where limits apply. Procedures explain how staff complete the work in a particular bank or system.
A company does not need a large treasury department to need a policy. The need usually appears when one or more of these conditions is true:
- cash is held across several banks or legal entities
- the business has external funding or debt obligations
- international activity creates currency exposure
- payment values have increased
- more people have bank access
- the board is reviewing runway, concentration or counterparty exposure
- surplus cash may be placed in notice, term or investment products
- finance decisions depend on one person's unwritten judgement
For an early stage company, the policy might be four pages and a limit schedule. For a multinational group, it may be supported by several standards and procedures. Length is not the measure. A policy works when staff can apply it and the board can monitor it.
The board normally approves risk appetite, delegated authority and material exceptions. Management implements the policy and reports against it. Finance or treasury maintains the operating data and proposes changes. Legal, tax, security and accounting specialists may review relevant sections.
What must a treasury policy contain?
Every policy should answer ten questions.
1. What is the objective?
State the order of priorities. A typical order is sufficient liquidity, preservation of capital, operational resilience and then return within the approved constraints. If the company has debt covenants or restricted cash, name them.
2. What is in scope?
List the legal entities, accounts, currencies and activities covered. State whether the policy applies to operating cash, customer money, restricted balances, debt, investments, foreign exchange, guarantees and intercompany funding. Exclude areas deliberately and point to the policy that governs them.
3. What liquidity must be available?
Define the minimum operating buffer and the forecast horizon used to assess it. The rule may refer to a number of months of approved operating costs, committed outflows or a stress scenario. State which balances count as immediately available.
4. Which counterparties and products are permitted?
Set eligibility criteria for banks, providers and products. Name the information used for review and who maintains it. Avoid relying on brand familiarity alone.
5. How is concentration limited?
Set limits by counterparty, banking group, product, maturity, currency or geography as relevant. Explain how connected institutions are treated and what happens when a limit is exceeded because balances change.
6. Who can prepare, approve and release transactions?
Include authority bands, separation of duties and entity specific requirements. Link the policy to bank mandates and platform permissions.
7. How are foreign exchange and funding decisions governed?
Define exposure, permitted instruments, hedging or conversion authority, intercompany funding types and documentation needs.
8. What reporting does the board receive?
Specify frequency, owner and minimum content. A useful report includes group liquidity, forecast, concentration, policy breaches, connection or access exceptions and material actions.
9. How are exceptions handled?
State who can approve a temporary exception, what evidence is required and when the board must be informed. An exception process prevents urgency from turning into an undocumented workaround.
10. When is the policy reviewed?
Set a regular review and event triggers such as a financing, acquisition, new country, material currency exposure, bank failure, control incident or major change in cash position.
How should counterparty and concentration limits be set?
Limits should express the company's risk appetite in numbers finance can monitor. Copying another company's percentages rarely works because cash needs, banking structure and obligations differ.
Begin by classifying cash according to purpose and required availability:
Next, define permitted counterparties. The board may consider regulated status, credit information, ownership group, operational resilience, country and the company's ability to access funds. The policy should state who checks these facts and how often.
Set concentration limits at the correct level. Two brands may belong to the same banking group. A deposit platform may provide access to several banks but the group still needs to understand the underlying placement, terms and access path. If protection schemes are relevant, obtain current eligibility information for the specific legal entity and institution rather than treating a general limit as a substitute for policy.
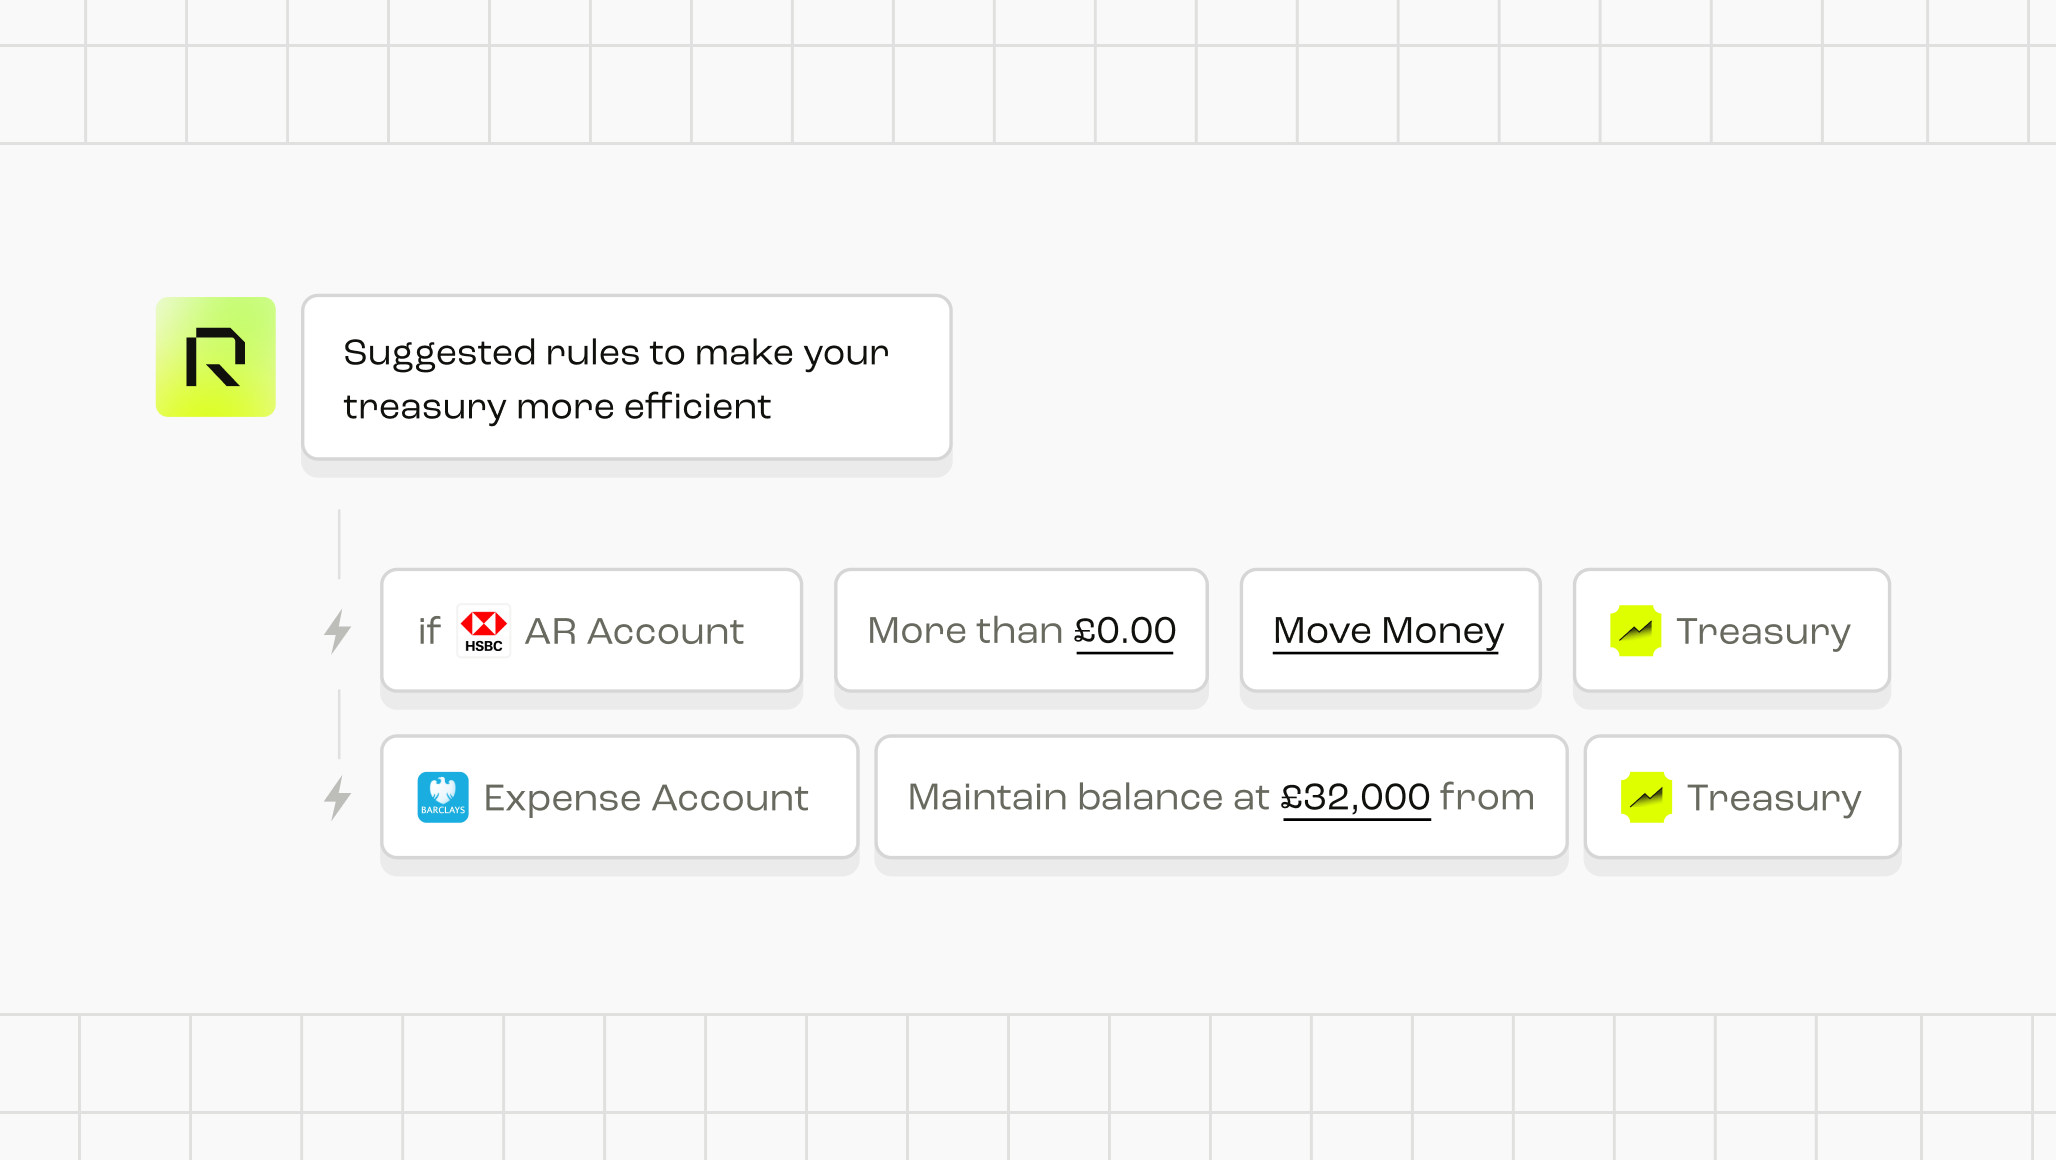
Limits can be expressed as a percentage of eligible cash, a fixed amount or both. A combined rule often works better. Percentage limits scale with the balance, while fixed limits prevent a sudden funding round from creating unintended exposure before the next review.
Define a cure process. A passive limit can be exceeded because receipts arrive or exchange rates move. The policy should distinguish a temporary passive breach from a deliberate new placement. State the notification time, approver and period allowed to return within limit.
Where the company considers money market funds or other investment products, product terms, liquidity, credit exposure, fees and accounting treatment require separate assessment. Capital may be at risk. The policy should define permitted categories and approval, not make a product recommendation.
Who is authorised to move money, and up to what value?
Authority needs more detail than “two approvers”. A strong matrix identifies the entity, transaction type, value, currency, beneficiary status and roles involved.
Separate four activities:
- Creating or changing a beneficiary.
- Preparing a payment or transfer.
- Approving the business decision.
- Releasing the transaction through the bank.
One person should not control the whole path for a material transaction. The exact separation depends on team size, but compensating review should be explicit where roles must overlap.
Use bands that reflect materiality. For example, routine supplier payments within an approved payment run may follow one route, while an unusual intercompany transfer or new investment product needs higher authority. The board should approve the framework and reserve only genuinely material or exceptional decisions.
Beneficiary changes deserve their own rule. Define independent verification, a cooling period where appropriate and escalation for changes received through email. Software can flag a change and preserve evidence, but the policy must say who verifies it.
Emergency authority should also be written in advance. Name eligible deputies, required evidence and retrospective reporting. Do not make shared credentials or informal chat approval the emergency plan.
Permissions must match the policy. Review bank mandates, treasury platforms and accounting access after approval. A document that says one thing while the bank allows another is not an effective control.
How often should the policy be reviewed and by whom?
The board should review the policy at least annually, with management reviewing limits and operation more frequently. The correct cadence depends on company change and risk.
A quarterly management review can examine:
- actual liquidity against the minimum buffer
- cash concentration by counterparty and product
- forecast accuracy and major variances
- policy exceptions and cure status
- users, mandates and access changes
- intercompany balances and ageing
- currency exposures and decisions
- provider or bank service incidents
Event driven review is just as important. Trigger a review after a material funding round, acquisition, entry into a new country, new debt facility, large change in runway, significant payment incident, bank concern or change in finance leadership.
The policy owner should prepare proposed changes with a short explanation. Legal, tax, accounting, security or investment specialists review sections within their competence. The board approves material changes to appetite, permitted activity and authority.
What does a board ready treasury policy look like? Template
The template below is designed to be copied and tailored. Replace every bracketed field. Delete sections that do not apply rather than leaving ambiguous boilerplate.
1. Purpose
The purpose of this policy is to ensure that [Group name] maintains sufficient liquidity to meet its obligations, preserves capital within the board's approved risk appetite, operates resilient banking and payment processes, and manages return only after the first three objectives are met.
2. Scope
This policy applies to [legal entities] and covers [bank accounts, deposits, investments, payments, foreign exchange, borrowing and intercompany funding]. It does not cover [excluded activities], which are governed by [other policy].
3. Roles
The board approves this policy, the limit schedule and material exceptions. [Committee or executive] oversees implementation. [Policy owner] maintains the group cash position, monitors compliance and reports exceptions. Transaction authority follows Schedule A.
4. Liquidity
The group will maintain immediately available liquidity of at least [amount or rule], measured against [forecast horizon and stress basis]. Restricted balances do not count towards this minimum. [Owner] reviews the calculation [frequency].
5. Permitted counterparties and products
Cash may be held only with counterparties meeting [criteria] and in products listed in Schedule B. [Owner] checks eligibility and supporting information [frequency]. Any new counterparty or product requires [approval].
6. Concentration and maturity
Exposure may not exceed the limits in Schedule B by [banking group, product, maturity, currency and geography]. A passive breach must be reported to [role] within [time] and corrected or approved within [period]. No deliberate transaction may increase a breach without prior exception approval.
7. Payments and access
Payment preparation, approval and release will follow Schedule A and applicable bank mandates. Beneficiary creation or change requires [verification]. Shared credentials are prohibited. User access is reviewed [frequency] and after every material role change or departure.
8. Intercompany funding
Intercompany movements must state purpose, entities, amount, currency, agreement or transfer type, approvals and accounting treatment. [Legal or tax review rule] applies. Receipt and both accounting entries must be confirmed.
9. Foreign exchange
Finance will report committed and forecast currency exposures above [threshold] for [horizon]. Permitted actions and instruments are listed in Schedule C. Every action requires [authority] and retained evidence. Speculative trading is prohibited.
10. Reporting
[Owner] provides [weekly or monthly] management reporting and [quarterly] board reporting covering liquidity, forecast, concentration, exceptions, access changes, intercompany positions, currency exposure and material actions.
11. Exceptions
Temporary exceptions require a written reason, amount or scope, risk assessment, approver, remediation owner and expiry date. Material exceptions require [board or committee] approval. Expired exceptions are treated as breaches.
12. Review and approval
This policy is reviewed at least annually and after a material trigger event. Version [number] was approved by [body] on [date], takes effect on [date] and is next due for review on [date].
Schedule A: authority matrix
Schedule B: counterparty and product limits
Schedule C: foreign exchange rules
Record permitted currencies, exposure thresholds, horizons, instruments, counterparties and approval bands. State how forecast confidence affects authority.
How to take the template to the board
Do not send the policy without the decisions highlighted. Give directors a short cover note containing:
- the current cash and banking shape
- the risks the policy is intended to govern
- the proposed liquidity minimum
- the proposed concentration limits
- the authority changes from current practice
- any specialist review completed
- the specific resolutions requested
Use examples. Show how the policy would handle a large customer receipt, a subsidiary funding request, a new bank account and an urgent payment. If directors can see the ordinary decisions, they can challenge the rules meaningfully.
After approval, turn the schedules into operating controls. Configure limits and permissions where the systems support them. Build a report that shows exceptions. Train preparers and approvers. Set the next review date immediately.
Sources
Frequently Asked Questions
Long enough to state scope, objectives, limits, authority, reporting and exceptions clearly. A growing company can often do this in a concise policy plus schedules.
The main policy can define eligibility, while a controlled schedule names approved counterparties and current limits. This makes routine updates easier to govern.
Only through the written exception process approved by the board. Define notification, authority, remediation and expiry in advance.
No. Diversification can reduce concentration, but operational, credit, liquidity, currency and access risks still need oversight.
Balance collection, limit monitoring, access reviews, exception preparation and reporting can be supported by software. Risk appetite, exceptional approval and transaction authority remain accountable human decisions.